All Categories
Featured
Table of Contents
Notes: GDP development is specified as the annual change in real (inflation-adjusted) GDP in the forecast year compared with the previous year. Joblessness rate is as of December for each year. Core inflation is the year-over-year change in the Consumer Prices Index, omitting unpredictable food, energy, alcohol, and tobacco costs, based on the fourth-quarter average for each year.
Yael Selfin, Vice Chair and Chief Financial Expert, KPMG in the UK, was joined by David Smith, Economics Editor at the Sunday Times and Chris Hearld, Group Managing Partner, KPMG, to check out how households and services could be affected and the challenge for the new government of providing development while managing public finances.
The world economy grew by 3.3 per cent last year, almost similar to the rates tape-recorded in 2023 and 2024. United States development slowed from 2.8 per cent in 2024 to 2.2 per cent in 2025, as tariffs, tighter immigration policy and elevated uncertainty weighed on need.

Growth in sophisticated economies is set to slow to 1.8 per cent in 2026 (US 2.3 per cent, Euro Area 1.3 per cent, Japan 0.8 per cent), with emerging markets growing by 4.0 per cent (China 4.6 per cent, India 6.5 per cent). US CPI inflation (2.7 per cent in December 2025) is expected to average 2.6 per cent in 2026, showing tariff pass-through and a weaker dollar.
Modern Banking Strategies for British Capital Markets
The ECB has actually held its policy rate at 2 per cent and is likely to maintain this stance. Long-lasting bond yields remain raised, with United States 10-year Treasuries around 4.3 per cent and Japanese 10-year government bond yields rising sharply to around 2.3 per cent, up from 0.3 percent in 2023. Tariff impacts are still resolving, while US actions in Venezuela, tensions over Greenland, and China's export controls on critical minerals raise the risks of more disturbance.
GDP grew by 0.7 percent in Q1 as companies brought forward activity ahead of the April increases in employer National Insurance Contributions and the National Living Wage. Development then slowed to 0.2 percent in Q2 and 0.1 per cent in Q3, held back by Budget-related unpredictability and a cyber-attack impacting Jaguar Land Rover.
The near-term outlook is supported by residual fiscal expansion and steady usage development. Beyond 2027, growth must settle a little above pattern at around 1.3-1.4 per cent. Given present population forecasts, this indicates per capita GDP development staying listed below 1 percent from 2027 onwards, highlighting the UK's persistent performance challenge.
Strategic Workforce Optimisation for Modern British Firms
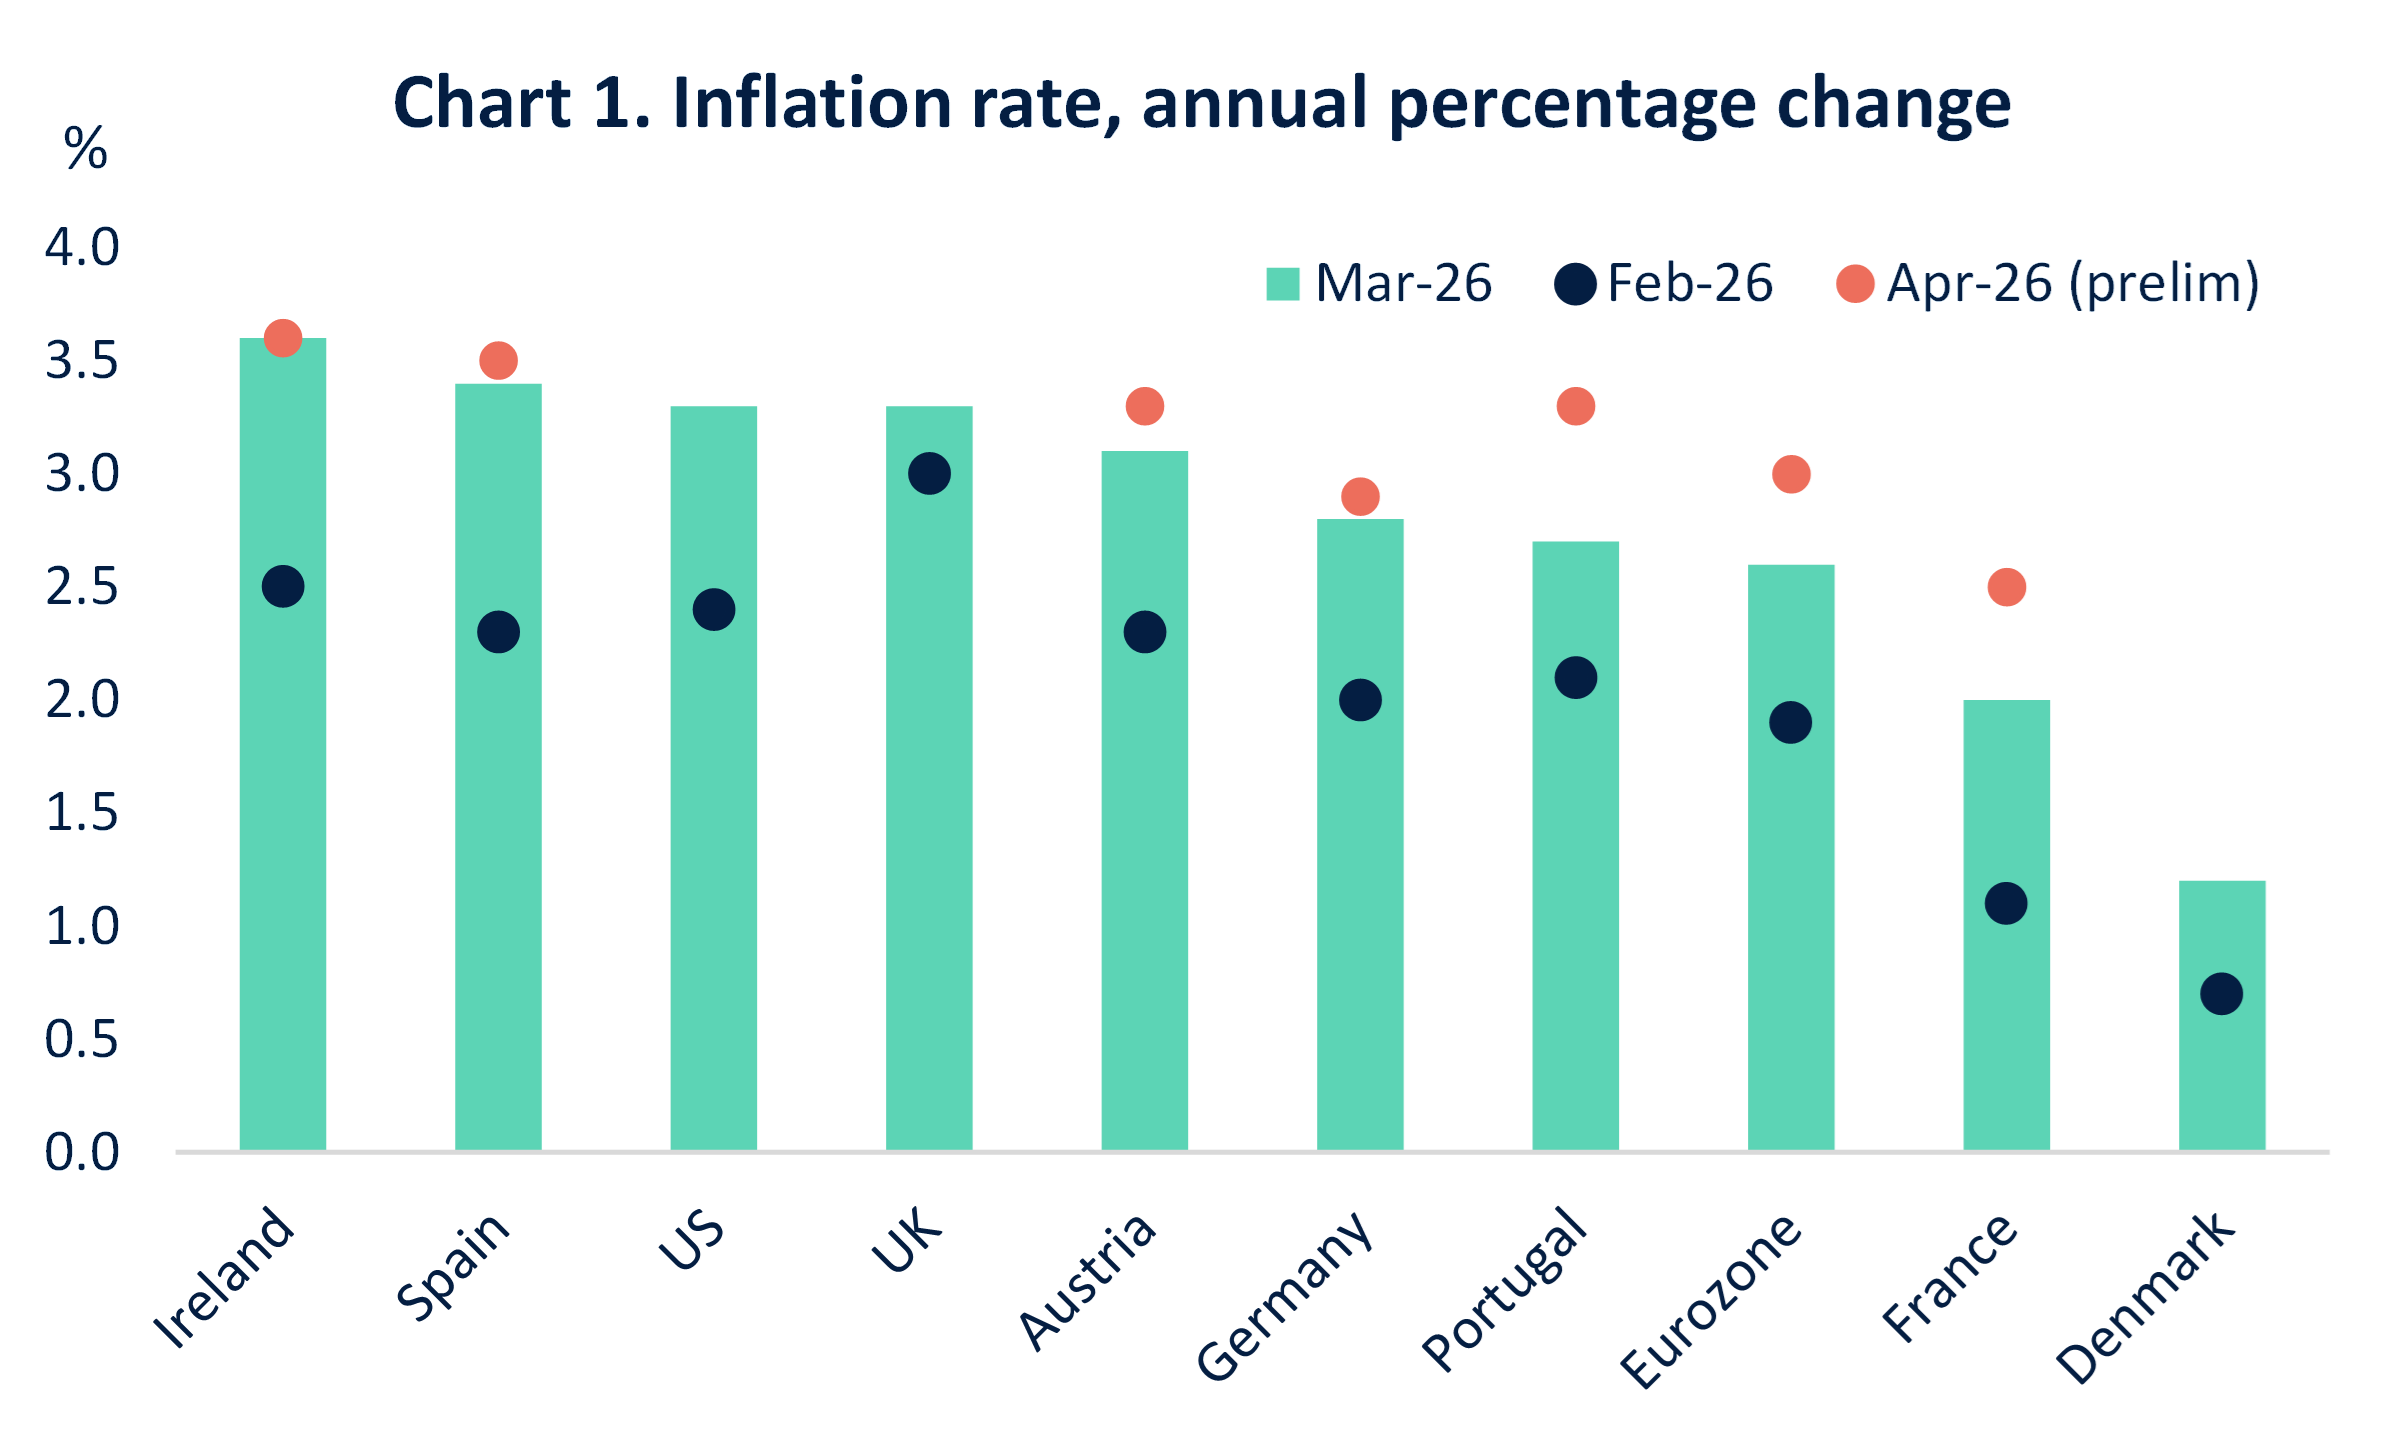
Our central projection is for CPI inflation to typical 2.3 percent in 2026 and to settle around target thereafter. However, services inflation (at 4.5 per cent in December) and core inflation (3.2 per cent in December) stay uncomfortably raised, indicating consistent underlying cost pressure. As examined in Box E of this Outlook, this shows mostly a sharp rise in labour supply as involvement increased, instead of extensive job losses.
Average profits development was 4.7 percent in the three months to November 2025. We project this to slow to around 3.6 per cent in 2026 and 3.1 percent in 2027 as increasing joblessness reduces employees' bargaining power a small amounts important for inflation to remain at target on a sustained basis.
This reflects sticking around uncertainty about the outlook and the scars from the recent inflation shock. We expect this raised cost savings ratio to continue, constraining intake growth to around 1.0 percent in 2026 and 1.3 percent in 2027. With inflation falling and joblessness rising, we expect two additional 25 basis point cuts in 2026, bringing the rate to 3.25 percent by year-endour estimate of the long-run neutral rate.
Strategic Workforce Optimisation for 2026 British Enterprises
On our forecast, the present spending plan is close to balance by 202930, indicating no effective headroomBox C takes a look at differences between the OBR's forecast and ours. Public financial obligation continues to rise, with the debt-to-GDP ratio approaching 100 percent by decade-end, restricting the scope for discretionary financial support in future shocks.
Evaluating Automated and Traditional Management StrategiesBy contrast, favorable net migration supports financial sustainability by expanding the working-age population and widening the tax base. Increases in employer National Insurance Contributions, considerable upratings of the National Living Wage (NLW), and reforms to work rights have actually raised the marginal expense of hiring by around 7 percent in real terms for an entry level position.

Latest Posts
Strategic Corporate Funding Projections for British Growth Sectors
Attracting Top Workforce for British Mid-Market Success
Future-Proofing UK Workforce Acquisition in 2026